A lot of Ontario cottages are bought with money borrowed against the house in the city. That makes cottage buyers some of the first people to feel a Bank of Canada hike, because home equity lines of credit move with prime the day after a decision. With the Bank expected to raise its policy rate to 2.50% on Wednesday, October 28, 2026, here is what changes for HELOC-funded cottage purchases, and how to protect the deal you are working on.
Decision watch: The Bank of Canada announces at 9:45 a.m. ET on October 28, 2026. We will update this article with the result shortly after. For down payments, insurance and seasonal versus four-season lending rules, see Cottage Mortgage Rules 2026.
Key takeaways
- A hike to 2.50% is the consensus call; markets priced the odds near 78% on October 23.
- Prime would likely rise from 4.45% to 4.70%, and most HELOCs move with it immediately.
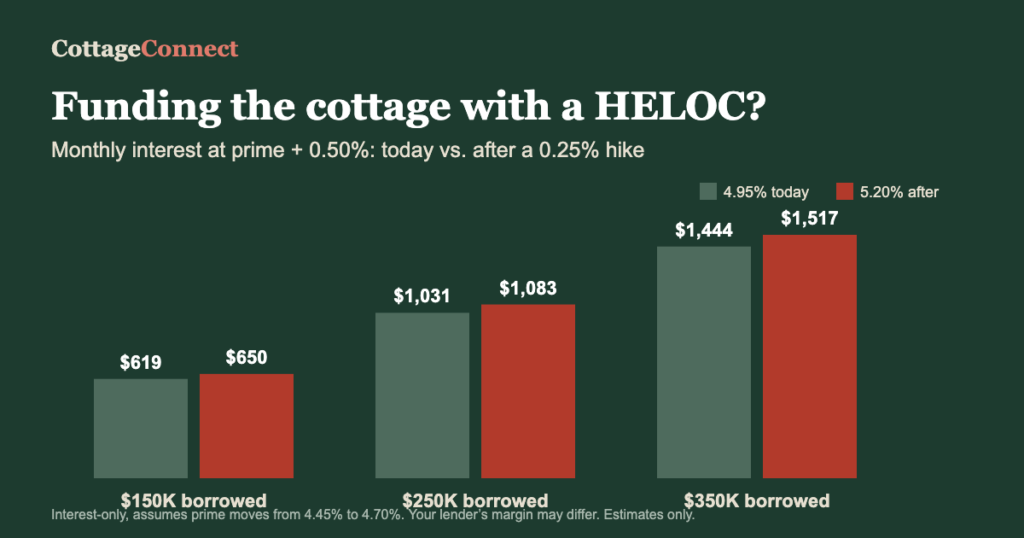
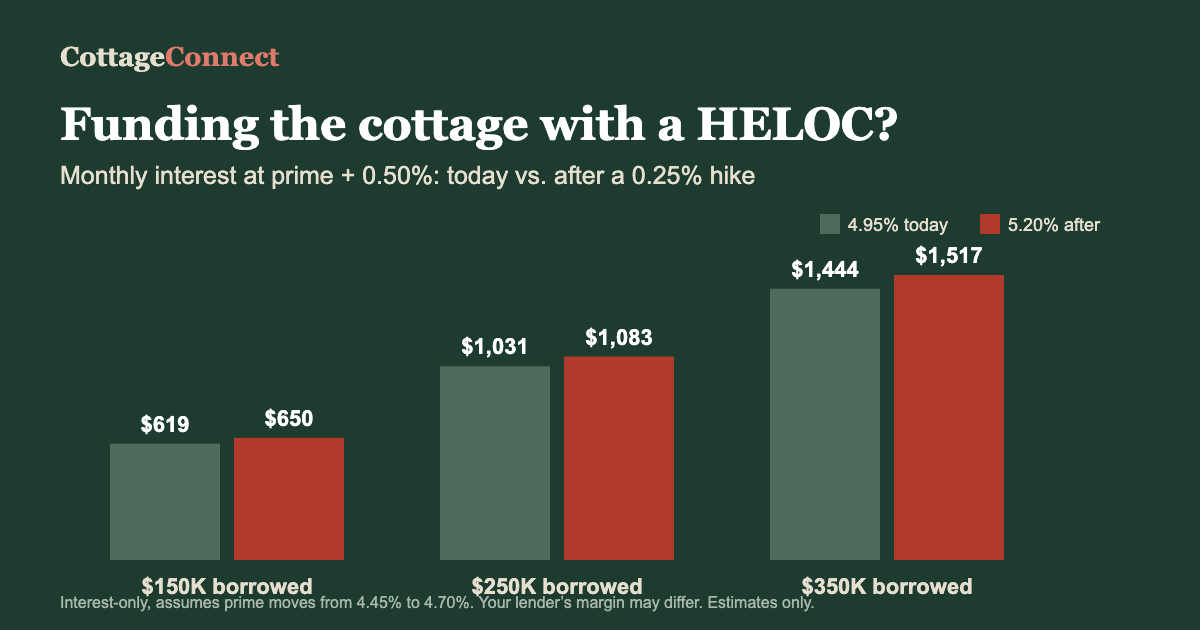
- At prime plus 0.50%, a $250,000 HELOC would cost about $1,083 a month in interest, up about $52.
- Your home’s revolving credit line is capped at 65% of its value, so the city house sets your cottage budget.
- The off-season gives patient buyers leverage, but plan around what you cannot inspect in winter.
Why cottage buyers feel this decision first
A first-home buyer with a fixed mortgage will not notice Wednesday’s decision until renewal. A cottage buyer often looks different: an owner with equity in a GTA home, drawing on a HELOC for the down payment or the full price, then carrying that balance at a floating rate. Every move in prime lands on that balance right away.
The reason a hike is likely is energy. Inflation rose to 3.1% in September on higher gasoline prices, and Governor Tiff Macklem warned that the risk of inflation broadening “has gone up.” A Reuters poll found 19 of 34 economists expecting a hike. The case for waiting rests on a weak job market, which lost 68,000 positions in September, and core inflation that is still under 2%.
What a hike does to a HELOC-funded cottage
| HELOC balance | Monthly interest at 4.95% | At 5.20% after a hike | Extra per year |
|---|---|---|---|
| $150,000 | $619 | $650 | about $375 |
| $250,000 | $1,031 | $1,083 | about $625 |
| $350,000 | $1,444 | $1,517 | about $875 |
Interest-only, assuming prime plus 0.50%. Your margin may be lower or higher.
One hike is manageable. The risk is the trend: Oxford Economics sees the policy rate at 2.75% by year-end, and most economists in the Reuters poll expect a second hike by March 2027. A HELOC has no end date and no payment schedule pushing the balance down, so the cost of a big interest-only balance can creep up for years.
Three ways to structure the purchase now
1. HELOC for the down payment, mortgage on the cottage
The most common setup. You borrow the down payment against the city home and take a separate mortgage on the cottage. Only the HELOC portion floats. Lenders count both debts when you qualify, at the stress-test rate, and seasonal cottages usually need a bigger down payment than four-season ones, as covered in our cottage mortgage guide.
2. HELOC for the whole purchase
Simple and fast, and it avoids lender rules about seasonal access, wells or septic. It also leaves the whole balance exposed to every rate move. Remember the cap: the revolving line on your home cannot exceed 65% of its value, and combined secured borrowing tops out at 80%.
3. Lock part of the line into a fixed term
Many readvanceable mortgages let you split part of a HELOC into a fixed-rate term. You give up flexibility and take on regular principal payments, but you cap your exposure if rates keep rising. Fixed rates follow bond yields, which have already risen this year, so get quotes before you decide.
Tip: If you plan to rent the cottage, keep the borrowing for the cottage separate from personal spending on the same line. Clean records make it easier to work out the tax side with your accountant. Our guide to renting your cottage covers the basics.
The off-season opening
Cottage buying slows after Thanksgiving, and higher borrowing costs give some buyers one more reason to wait for spring. That is when motivated sellers, especially those carrying two properties, become more flexible. Our cottage prices by region shows where buyers already have the most leverage, and our region pages for Muskoka, Haliburton and the Kawarthas show how long listings are sitting.
The trade-off is what you cannot see under snow: shoreline, dock condition, septic performance and seasonal road access. Read buying a cottage in fall or winter before you waive anything.
Before you sign anything this week
- Ask your bank for your HELOC margin over prime and what your available limit will be after the purchase.
- Get a cottage mortgage pre-approval with a rate hold if you are using one, before 9:45 a.m. Wednesday.
- Stress your budget at prime of 5.00%, roughly what two more hikes would mean.
- Price both properties as a pair. If selling the city home is part of the plan, check what your cottage or home is worth and our view on selling in the fall.
Frequently asked questions
Can I use a HELOC on my house to buy a cottage?
Yes. Many Ontario buyers draw on a home equity line of credit for the cottage down payment, or for the whole purchase on a lower-priced property. Under federal rules the revolving line on your home is capped at 65% of its value, and total secured borrowing at 80%.
How does a Bank of Canada rate hike affect my HELOC?
Most HELOCs are priced at prime plus a margin, and banks usually move prime within a day of a Bank of Canada decision. If the Bank raises its rate 0.25 points, prime is expected to go from 4.45% to 4.70%, adding about $52 a month in interest on a $250,000 balance.
Should I lock my HELOC into a fixed rate before buying a cottage?
Many readvanceable mortgages let you move part of a line of credit into a fixed-rate term. It protects you from further hikes but usually means regular principal payments and a penalty to break. Ask your lender to quote both before you firm up a purchase.
Is fall or winter a good time to buy a cottage?
Fewer buyers shop for cottages after Thanksgiving, which can mean more room to negotiate, but you cannot see the waterfront, septic or road access in their summer condition. Build inspections and conditions around that.
The full picture, reserved for members
Browse cottages and waterfront for sale across Ontario, with sold history on every listing, or try Cottage Swipe to sort the shortlist from your couch this winter.
General information as of October 27, 2026, not mortgage, tax, legal or financial advice. Interest figures are estimates. Confirm your situation with a licensed mortgage professional and your accountant. Sources: Bank of Canada, Statistics Canada, OSFI Guideline B-20, Reuters poll (October 21 to 23, 2026), LSEG.